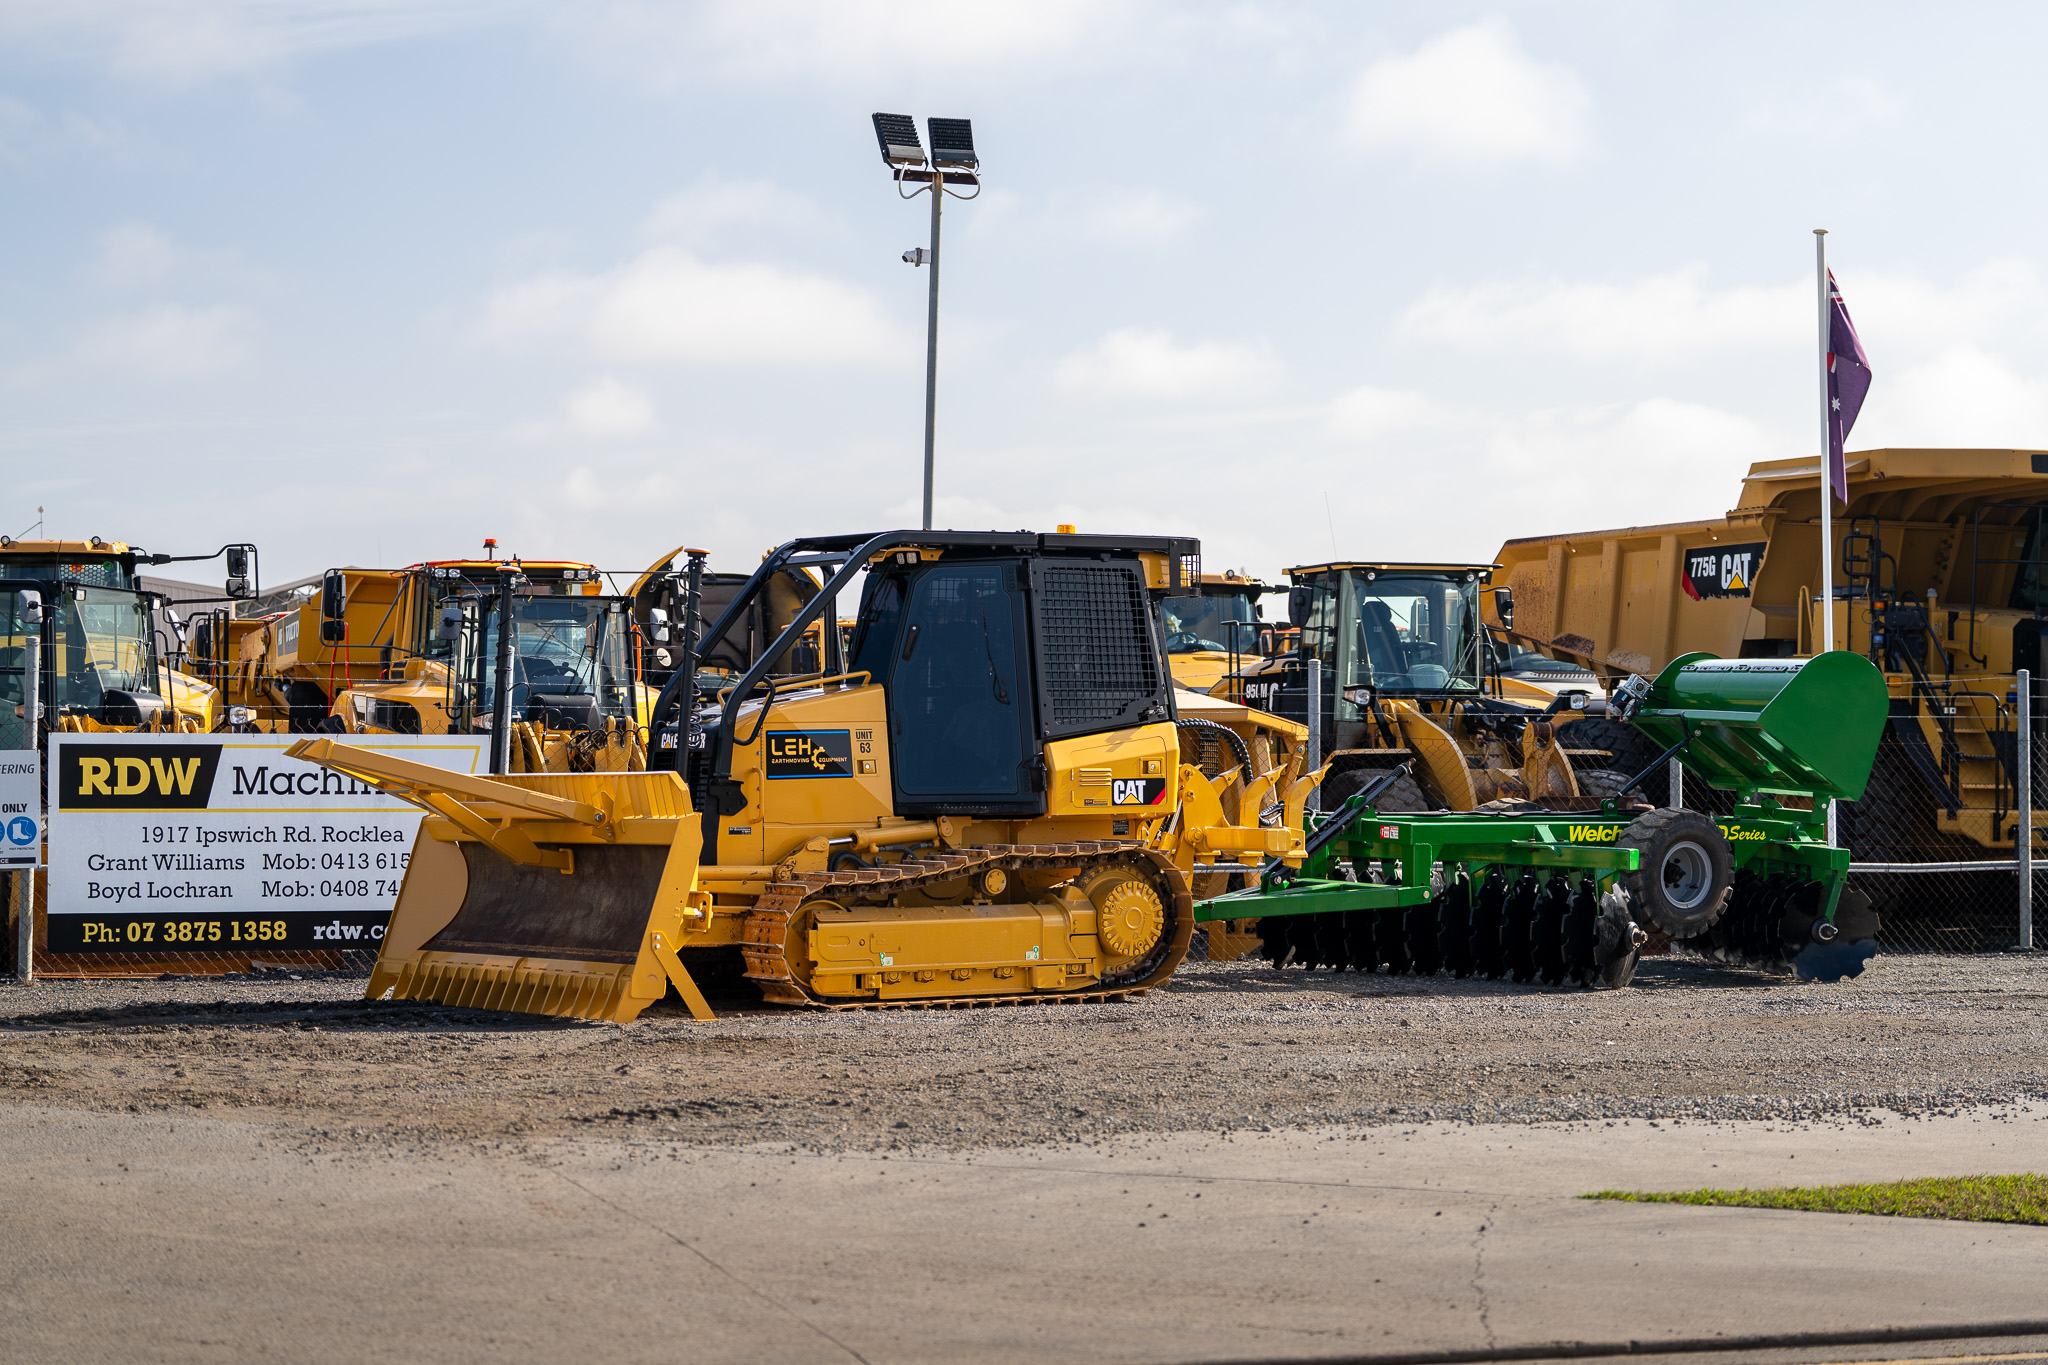

A new bank relationship has to account for the fleet, not just the overdraft.
Look beyond the headline facility
A bank change can touch more than the business loan or overdraft. Equipment facilities, guarantees, account conduct, security over assets and upcoming purchases may all be connected. A proposed bank could like the operating business but still want a different view of its machinery exposure.
Before approaching a replacement bank, we map what the current bank actually provides and what will need to be transferred, repaid or retained. This includes the facilities that are easy to overlook because they are not being actively drawn today.
Keep the fleet working during the change
If existing equipment contracts are staying where they are, the incoming bank needs to understand that exposure. If some contracts must be refinanced, we need current payouts and a sensible timeline. The aim is to avoid discovering a security or documentation issue just as a machine needs to be delivered.
It also pays to explain the next twelve months of capital spending. A rebanking proposal that covers today’s debts but leaves no room for next quarter’s fleet replacement is incomplete.
Bring the right people together
The owner, accountant, banker and equipment finance specialist may each see a different part of the picture. We can help put the asset and lender schedule beside the financial accounts so the new relationship is assessed as one business, with a plan for what happens after the move.
Every business, asset and lender is different. Talk through your circumstances with your advisers before making a finance decision.